 A Message From Brownstone Research Former tech executive Jeff Brown, the man who picked Nvidia in 2016, before it jumped as high as 37,800%, just got inside a Cybercab, Elon Musk's new car that has no steering wheel or pedals… and what happens will shock everyone. Click here to see the details or read more below.
Dear Reader, In April 2026, Elon Musk announced he was partnering with Intel. The result? Shares took off… And were trading 177% higher just two months later. I believe Elon is about to announce a NEW partnership with this little-known company… To work on what he called "the most epic AI project in history." But you need to act fast… Because Elon has already approached this company. I believe he's going to make it official by October 30… Which should send shares higher than anyone can imagine. Click here to see the details. We have so much to look forward to, Jeff Brown
Founder & CEO, Brownstone Research
Today's Bonus News
Kinder Morgan's $4.7 Billion Pipeline Bet Could Be Bigger Than Its Earnings BeatSubmitted by Thomas Hughes. Publication Date: 10/23/2026. 
Key Points
- Kinder Morgan posted strong Q3 results, with revenue up 9.2% and earnings per share rising 21%, prompting analysts to reaffirm or raise price targets.
- The company is adding two major natural gas pipelines backed by long-term distribution agreements, including one serving data centers tied to an unnamed hyperscaler.
- Kinder Morgan's cash flow covers its dividend more than twice over, supporting sustainable annual increases, though institutional selling and regulatory approvals remain near-term risks.
- Special Report: You missed yesterday's deadline…
Kinder Morgan (NYSE: KMI) is a growing company with highly visible revenue and cash flow. While that visibility can limit stock price action by enabling the market to accurately price in the outlook, Kinder Morgan’s trends are bullish—the market is perpetually catching up with an improving outlook. Key details from the third-quarter results include monetizing prior investments, along with $4.7 billion in newly approved pipeline investments representing the company’s share of two joint ventures. The takeaway is that Kinder Morgan, which primarily self-funds its growth, is adding two major natural gas pipelines to its network. Backed by long-term distribution agreements, the projects reinforce its growth trajectory and visibly increase its long-term revenue-generating and cash-flow potential. Its stock price could follow. Both projects are expected to begin service in 2030, subject to regulatory approvals.
Analysts are generally supportive of this thesis. Recent activity has included reaffirmed ratings and price-target increases, strengthening the trend. While consensus forecasts only modest upside from recent share prices, they point to a new high and are rising in 2026, while the high-end target implies double-digit upside. The likely outcome is that Kinder Morgan continues expanding its network, growing sales volume and revenue and keeping analysts and KMI investors bullish over the long term. 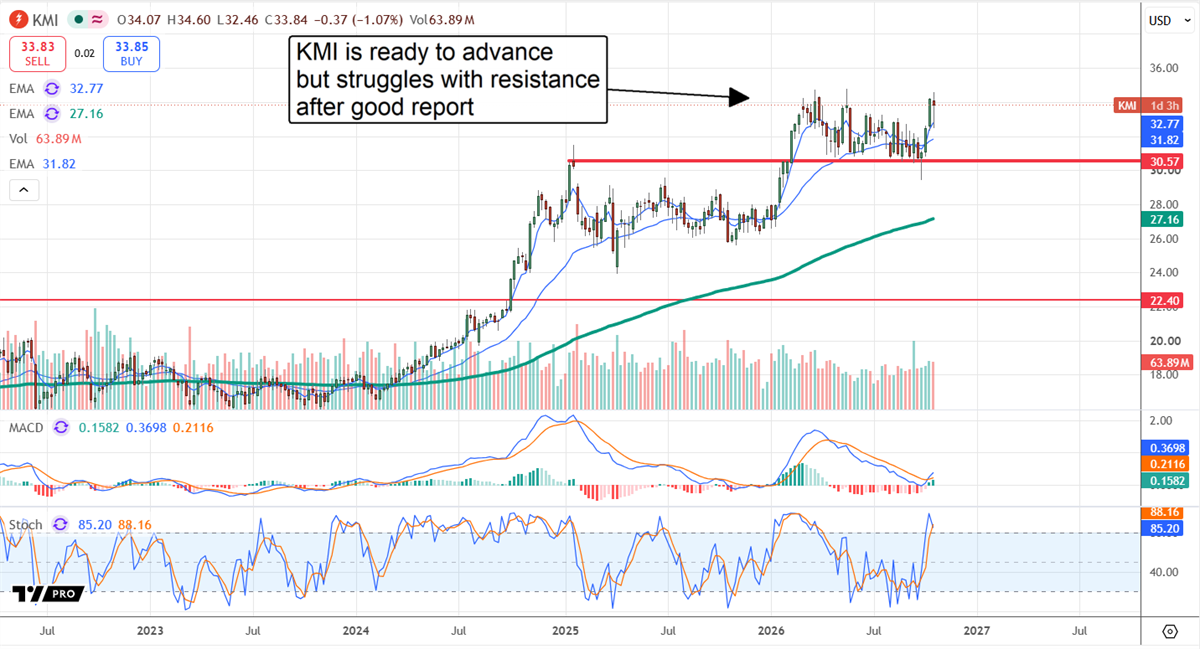
Kinder Morgan Outperforms: Dividend Increases Are ComingKinder Morgan had a good third quarter, with revenue up 9.3% to $4.53 billion and beating analysts' estimates by approximately 3.7%. Strength was underpinned by capacity expansion and demand, specifically for natural gas used in power generation, industrial applications and exports. More importantly, that strength helped drive operating leverage, enabling accelerated earnings growth in nearly all comparisons. Adjusted EBITDA grew 9%, trailing revenue slightly, but a 22% increase in net income and 21% growth in both GAAP and adjusted earnings per share (EPS) helped offset that, along with an improving outlook for capital returns. Kinder Morgan did not adjust its 2026 budget but raised its expectations for how far results will exceed it, including adjusted EBITDA by more than 6% and adjusted EPS by more than 13%. This leaves the company in better shape than expected, with excess cash flow after paying dividends and capital expenditures. Investors should not misinterpret dividend safety, which can sometimes look strained relative to actual EPS. The company is a cash-flow machine that pays dividends based on cash flow and targets sustainable annual increases with ample cash-flow coverage. During the first nine months of 2026, operating cash flow was more than twice the amount paid in dividends, while dividends consumed about 90% of free cash flow after capital expenditures. The yield is around 3.5% as of late October. Institutions may provide a headwind in the fourth quarter. The group provides a solid support base, owning about 63% of the shares and accumulating them over the past year, although some institutions have reported reduced holdings in recent filings. Those filings do not establish that the selling occurred immediately before earnings. Renewed institutional selling could reinforce signs of market resistance and keep the stock from advancing if distribution persists. The question is whether the third-quarter results can prompt institutions to adopt a more bullish posture, and the odds are high that they can. Kinder Morgan Helps Unstick AI BottleneckThe market should not overlook the nature of the new projects. One is in the Southeast, one of the nation's fastest-growing demand centers, while the other will support power generation for data centers. It will transport natural gas from the Permian Basin north toward the Texas Panhandle to support new electricity generation. While the customer has not been publicly named, Kinder Morgan described it as an A-list hyperscaler. That is important because natural gas connections can help address power-grid constraints by supplying fuel for dedicated power generation, potentially including fuel cells from companies such as Bloom Energy (NYSE: BE). However, Kinder Morgan has not disclosed the customer's generation technology. The new pipeline is a big deal not only for KMI but also for the AI and data center industries. Existing and new projects will focus on locations where power and/or gas infrastructure already exists. Investors should not mistake visibility for a no-growth environment. While visibility means significant surprises are unlikely and big gains get priced in quickly, a slow-growth environment can still drive value. In this scenario, KMI shares can trend higher over time, providing a dual tailwind for portfolio growth, as they have over the last few years. The caveat is that share-price appreciation may come in fits and starts, as it has over the past few years, with price surges followed by prolonged consolidations. Kinder Morgan’s risks are operational, execution-related and regulatory. Operationally, it faces high maintenance costs, litigation and third-party damage to its infrastructure. Execution risks are tied to project timelines and completions, including costs and budgets. Regulatory risk is critical because regulators have the final say on whether projects receive approval. Both newly announced projects are awaiting final regulatory approval. . |


Comments
Post a Comment