Key Points
- Despite a U.S.-China agreement to address critical mineral supply chains, domestic rare-earth production still covers less than half of U.S. demand, ensuring continued reliance on China.
- MP Materials dominates U.S. rare-earth mining and magnet production, with strong revenue growth, while Energy Fuels diversifies into uranium production to hedge against rare-earth price pressure.
- NioCorp Developments offers high-risk, high-reward exposure through its unbuilt Nebraska project, which analysts project could deliver substantial long-term upside despite significant financing hurdles.
- Special Report: “Elon’s nightmare” could fund your retirement
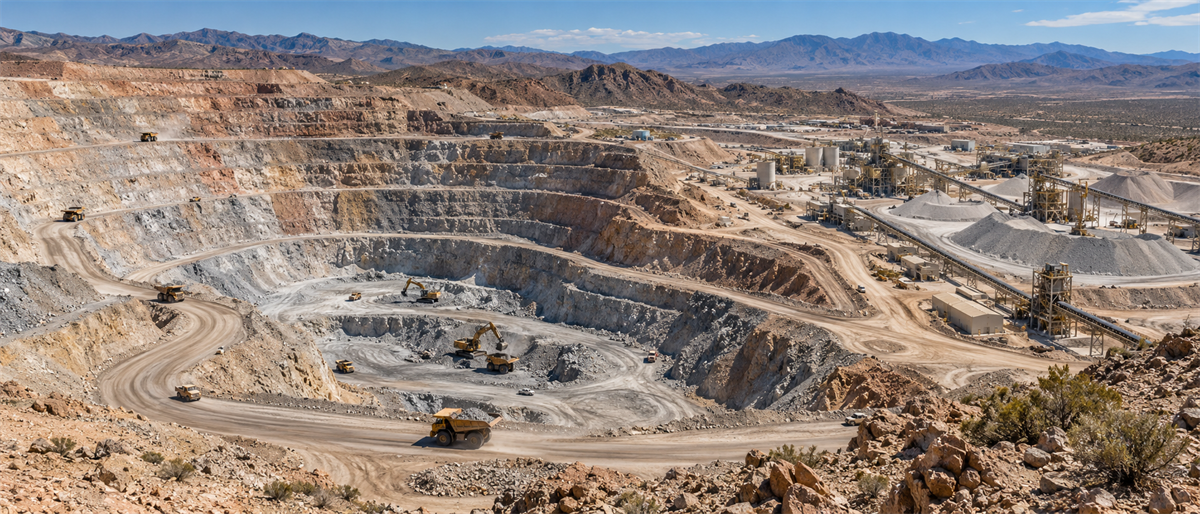
At their Sept. 24 summit, Presidents Trump and Xi agreed that the United States and China would continue working toward resolving supply chain issues related to critical minerals. Rare-earth shipments nonetheless remain constrained—and U.S. rare-earth mining continues to lag behind Chinese production. Domestic production doesn't even cover half of domestic demand, so it's likely that the United States will remain heavily dependent upon China for rare earths for years to come.
Whether the U.S.-China diplomatic relationship yields a long-term détente, a confrontation, or something in between, there may nonetheless be strong incentives for domestic minerals companies to bolster U.S. rare-earth production in the years to come. Several companies in a variety of different stages of growth could all benefit, although some certainly remain more speculative than others.
MP's Domestic Dominance Is Essential Regardless of China
With a market capitalization above $8 billion, MP Materials (NYSE: MP) is one of the largest rare-earth miners in the country. Recently, the firm has leaned into downstream production and is now an increasingly prominent producer of rare-earth magnets in the domestic industry as well.
MP's business is likely better positioned for an ongoing tense relationship between the United States and China in mind—to the extent that the two countries reconcile over critical minerals, it could lead to an increase in the supply of both raw materials and downstream products in the United States, eliminating a scarcity premium and pressuring MP's upstream business as well.
Still, the production imbalance between the two countries—coupled with MP's dominant status in the United States—may make MP's domestic production critical regardless of what ends up happening diplomatically.
With significant production gains and revenue that surged by 89% year over year (YOY) last quarter, MP has solidified its dominance within the U.S. rare-earth industry. Investors will pay a premium for that status, however, as its shares carry a lofty sales multiple. That may not matter, however, if analyst predictions of more than 62% in upside potential come to pass.
UUUU Balances Rare Earths Against Uranium for Diversification
Energy Fuels Inc. (NYSEAMERICAN: UUUU) provides exposure to rare-earth metals, but it is also a leading producer of uranium, with exposure to mineral sands and a variety of other products. This diversification is perhaps its strongest benefit; even if the pipeline of rare earths from China opens up and Energy Fuels faces pricing pressure, it can lean on its uranium business.
In the latest quarter, that business did quite well, generating some $25 million in revenue based on 310,000 pounds of uranium sold. Despite its advantages as the operator of the sole conventional uranium mill in the United States, Energy Fuels faces risks, including profitability challenges, the need to balance multiple long-term development projects, and more. Still, with an average price target of $21.85, analysts predict UUUU has nearly 120% in possible upside.
NB's Nebraska Project Could Pay off, But Many Hurdles Remain
Investors may be drawn to NioCorp Developments Ltd. (NASDAQ: NB) for its potential in a Nebraska project that could eventually yield a wide range of rare-earth minerals. The company has projected a 40-year mine life and a net present value (NPV) of $4.1 billion, pre-tax, both of which signal the possibility that this could be a foundational operation for the firm.
However, the giant caveat is that the project is not yet a producing mine, and NioCorp still needs sufficient project financing before it can fully build out its operations. The firm is therefore a longer-term bet, and one that may not be as directly impacted by near-term U.S.-China relations. Of course, the possibility of financing falling through, coupled with a share count expansion that has already been sizable, means that the risks to investors are significant.
This high-risk, high-reward status may be why analysts caution that NB shares are a Hold, even as the company has more than 160% in projected upside potential.
The strongest U.S. rare-earth companies may be able to thrive regardless of the trade relationship between the United States and China because of the need for a domestic rare-earth supply chain, or because they are able to present diversification beyond that core group of minerals. With uncertainty surrounding the geopolitical environment, investors might either choose to look for an established name with a known presence or be even more inclined to take a big risk on an up-and-coming firm like NioCorp.
Read this article online ›
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
Get Text Alerts from American Market News (free)


Comments
Post a Comment