 This has been disseminated on behalf of A2Z Cust2Mate Solutions Corp. The Shopping Cart is Becoming a Digital Revenue Machine and A2Z Cust2Mate (NASDAQ: AZ) is Building a Platform that Could Monetize Every Cart in More Ways Than One! 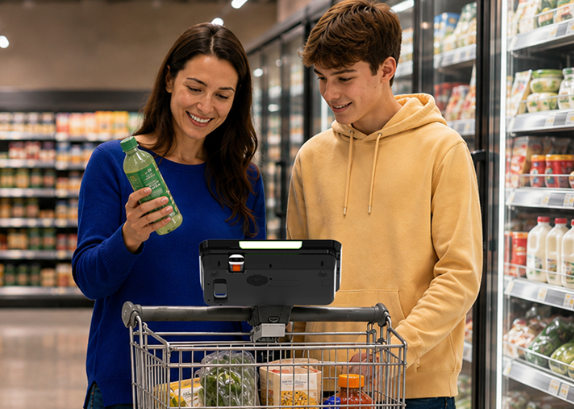
New News Today! A2Z Cust2Mate Completes Acquisition of In-Store Retail Media Business Hedia This acquisition adds an established retail media business with approximately $20 million in annual revenues, advertiser relationships and campaign execution capabilities! A2Z Cust2Mate Solutions Corp. (NASDAQ: AZ)is taking one of the most overlooked pieces of retail infrastructure and turning it into a connected technology platform. Its detachable SmartPanel can transform existing shopping carts into digital touchpoints for personalized promotions, guided shopping, scan-and-pay checkout, AI-powered loss prevention and real-time shopper engagement. But the bigger story is what happens after the cart is deployed: AZ can potentially generate recurring revenue from multi-year Smart Cart subscriptions while also opening the door to retail-media advertising and shopper data and analytics. With a $195M+ contracted order book and approximately 19,000 carts scheduled through 2027, AZ is moving far beyond the traditional pilot-stage smart-cart story. The company's recent HaStock developments highlight how that platform can expand. HaStock increased its total commitment to 3,050 Smart Carts, including 1,050 additional carts valued at approximately $11 million over five years, while a separate August agreement gave AZ in-store retail media and advertising rights across HaStock stores in addition to its existing on-cart media rights. Meanwhile, Q2 revenue reached $5.9 million, up 409% year over year, as deliveries accelerated. AZ isn't simply putting screens on shopping carts, it's building a connected retail ecosystem where the same installed network can potentially generate commerce, advertising and intelligence revenue. See why AZ's connected-cart strategy could be one of the more interesting stories developing in retail technology out there!
More Reading from MarketBeat Media
Alamos Gold’s 1 Million-Ounce Growth Story Is Hiding in Plain SightWritten by Jeffrey Neal Johnson. Originally Published: 10/2/2026. 
Key Points
- Alamos Gold saw a 673% spike in bullish call options volume, suggesting investors expect a company-specific rebound despite falling gold prices.
- Shares fell after seismic events damaged the Young-Davidson mine, prompting a 12% production guidance cut, but management called the issue temporary.
- Alamos Gold maintains strong margins, low debt, and institutional support, funding a self-financed plan to double output to 1 million ounces by 2030.
- Special Report: The tiny optical part behind the AI smart glasses boom
While the broader commodity market faces downward pressure, a sudden surge in bullish options volume for a specific mid-tier miner indicates that institutional capital may be buying the dip. Derivatives traders are looking past temporary geomechanical disruptions and viewing the recent equity sell-off as a mispriced entry point ahead of a fully funded expansion pipeline.
Alamos Gold (NYSE: AGI) recently experienced a 673% spike in call options volume, with nearly 34,000 contracts traded in a single session. This influx of upside positioning contrasts sharply with a recent pullback in spot gold prices. It suggests that investors are pricing in a localized, company-specific rebound that is detached from broader macroeconomic headwinds. Options Flow Signals a Gold DisconnectNormally, gold equities trade in lockstep with the underlying commodity. When spot prices decline, mining margins shrink, and equities typically follow suit. Yet traders executed an approximately $2.9 million sweep at the ask for Alamos Gold’s $31 calls expiring Oct. 16, 2026. This occurred even as spot gold prices declined about 14% over the quarter. This divergence is notable. Options flow of this magnitude, particularly when heavily concentrated in near-term call contracts, suggests that investors anticipate an impending catalyst or view the approximate 15% year-to-date decline as fundamentally unjustified. The derivatives market often acts as a forward-looking mechanism. Right now, it is signaling that the market may have overreacted to a recent operational setback. Looking Past Temporary Seismic TremorsTo understand Alamos Gold's recent stock price weakness, investors should look at the Young-Davidson mine in Ontario. In mid-June 2026, two seismic events damaged infrastructure and temporarily cut off access to several high-grade stopes. Mining rates at the facility are expected to fall from a targeted 8,000 metric tonnes per day to around 5,000 tonnes through the remainder of the year. Management subsequently reduced full-year production guidance by 12%. The market quickly priced in this shortfall, pushing shares down about 10% over the last month. However, fundamental analysis suggests that this is a temporary geomechanical hurdle rather than a structural impairment to long-term cash flow generation. Underlying financials support this view. Alamos Gold generated $594 million in second-quarter revenue, producing adjusted earnings per share of 59 cents. Net margins sit near 52%, and Alamos Gold generated about $144 million in quarterly free cash flow. This liquidity allowed the company to pay its scheduled dividend on Sept. 24, signaling management's confidence in the balance sheet despite the production reset. Sustaining a capital return program during an operational disruption is a strong signal of financial health. It shows that Alamos Gold has the internal capital required to weather localized challenges without diluting shareholders. Blueprint for a Million-Ounce FutureThe options market is likely looking past the 2026 production dip and focusing on the company's long-term expansion strategy. At the Mining Forum Americas 2026, management reiterated its target of scaling annual gold output from roughly 500,000 ounces to 1 million ounces by 2030. This growth pipeline relies heavily on the Island Gold Phase 3+ shaft expansion, development of the Lynn Lake project and increased throughput at the Magino mill. The strategic acquisition of the Magino mine is particularly notable. By integrating the Magino mill with its existing Island Gold operations, Alamos Gold can centralize processing, reduce redundancies and structurally lower all-in sustaining costs across the district. Lowering the cost per ounce is a critical defense against commodity price volatility. Because Alamos Gold operates with a nearly unleveraged balance sheet, featuring a debt-to-equity ratio of just 0.04 and a current ratio of 2.07, these expansion projects are internally funded. Alamos Gold does not need to access tight credit markets, take on expensive debt or issue equity to reach its 1-million-ounce target. This financial flexibility, paired with unhedged exposure to future gold prices, makes the 2030 growth plan highly credible to institutional investors assessing the mid-tier mining landscape. A self-funded growth model reduces execution risk and ensures that shareholders capture the full upside of the expanded production profile. Valuing the Underground Expansion PhaseLarge institutions are actively accumulating shares, providing a structural floor beneath Alamos Gold. According to recent 13F filings, Andra AP fonden increased its stake by nearly 140%, adding 181,100 shares. Other funds, including Engineers Gate Manager LP and Tidal Investments LLC, also expanded their positions. Institutions currently command over 64% of the outstanding float. This level of institutional sponsorship typically helps smooth volatility and provides a base level of demand during broad market sell-offs. Tier-one research desks align with this institutional optimism. RBC Capital recently reiterated an Outperform rating with a $42 price target, while National Bank maintained a similar Outperform stance. Broader valuation metrics show Alamos Gold trading at a trailing price-to-earnings ratio of about 11.9 and a forward multiple of 15.6. The price-to-earnings-growth ratio (PEG) sits at just 0.44. A PEG ratio below 1 often indicates that a company's earnings growth is not fully reflected in its current valuation. Among the nine Wall Street analysts covering Alamos Gold, the consensus rating is Moderate Buy, with an average price target of $47.50. That target represents an approximate 45% premium to current trading levels. Weighing the Motherlode PotentialInvestors assessing the mining sector often weigh the risks of operational delays against the potential for free cash flow generation. Recent seismic events at Young-Davidson highlight the inherent geological risks of underground mining. If similar disruptions occur or if the Phase 3+ expansion faces capital overruns, Alamos Gold could face additional pressure. Yet the combination of an unleveraged balance sheet, high net margins and a fully funded path to doubling production by 2030 creates an asymmetric setup. The options market is treating the Young-Davidson disruption as a mispriced entry point. As Alamos Gold works through its temporary operational headwinds and ramps up the Island Gold expansion, the underlying cash flow metrics should begin to reflect its expanded production capacity. Investors evaluating commodity exposure may want to monitor the execution of the Island Gold Phase 3+ expansion in the coming quarters, as consistent progress there will likely be the primary catalyst for long-term price appreciation.
This message is a paid advertisement for NASDAQ:AZ from Smallcaps Daily and Interactive Offers. MarketBeat Media, LLC receives a fixed fee for each subscriber that clicks on a link in this email, totaling up to $14,000. Other than the compensation received for this advertisement sent to subscribers, MarketBeat and its principals are not affiliated with either Smallcaps Daily or Interactive Offers. MarketBeat and its principals do not own any of the stocks mentioned in this email or in the article that this email links to. Neither MarketBeat nor its principals are FINRA-registered broker-dealers or investment advisers. The content of this email should not be taken as advice, an endorsement, or a recommendation from MarketBeat to buy or sell any security. MarketBeat has not evaluated the accuracy of any claims made in this advertisement. MarketBeat recommends that investors do their own independent research and consult with a qualified investment professional before buying or selling any security. Investing is inherently risky. Past-performance is not indicative of future results. Please see the disclaimer regarding NASDAQ:AZ on Interactive Offers' website for additional information about the relationship between Interactive Offers and NASDAQ:AZ.
. |

Comments
Post a Comment