 A Message From Brownstone Research Dear Reader, Do you hold any of these AI stocks? 
Wall Street insider Jason Bodner — the man who called Nvidia at $4.50 — says today’s AI stocks are about to hit a wall. And a completely different group of AI firms… names Wall Street is starting to ignore… are about to take off. This has nothing to do with SpaceX… A new chatbot… Autonomous robots… Or anything you’re likely hearing about. It has to do with a brand-new “light-speed” device turning AI as we know it into “Accelerated AI”… Making it 100 times faster… And 100 times more energy efficient — right here, on Earth. Already, some of the biggest tech investors like Elon Musk, Mark Zuckerberg, Cathie Wood, and Bill Gates are moving money into it. Just to name a few… They’re all moving money to prepare for what’s coming. But you won’t hear anything about it in the mainstream news… In fact, TV pundits spent most of this past year talking about AI worries and its “existential risk” to jobs… Or arguing whether we’re in an AI bubble and when it would pop… That’s why most Americans won’t see it coming until it’s too late. Don’t be one of them… Because if you’re holding the wrong AI stocks when “Accelerated AI” goes mainstream… You could spend the next decade just trying to claw back to even… But if you make the one move Jason reveals in this urgent video message… The next 12 to 24 months could hand you bigger gains than the entire AI boom of the last three years. Click here to hear the full story and get ahead of the crowd. But hurry, because this opportunity won’t stay hidden much longer. We have so much to look forward to, Jeff Brown
Founder & CEO, Brownstone Research P.S. Jason also shares details on 10 popular AI stocks he says you must dump before this shift goes mainstream. Names sitting in millions of 401(k)s, IRAs, and brokerage accounts. Click here to see if yours made the list.
Just For You
ASML Can’t Keep Up With AI Demand—Why That's a Good ThingBy Thomas Hughes. Date Posted: 10/15/2026. 
Key Points
- ASML's CEO said demand will exceed supply through 2028, even after planned 30% capacity increases over the next two years.
- The company posted mixed Q3 revenue but stronger margins, raised full-year guidance and issued a strong forecast for the fourth quarter.
- Analysts maintain a consensus Moderate Buy rating with roughly 25% upside, while technical charts and capital returns point to further gains.
- Special Report: Jeff Bezos will be on his knees
ASML (NASDAQ: ASML) sent two strong signals in its Q3 report: one company-specific and the other relevant to the broader AI industry. The company-specific signal is that demand is high—so high, in fact, that planned capacity increases of 30% over the next two years won’t be enough to meet it. According to CEO Christophe Fouquet, demand will exceed supply through 2028, forcing the company to make critical decisions, including ramping production and expanding its plans for new capacity. Industry signals are also robust.
The industry-specific signal is that demand remains strong across computing and memory, with supply constraints likely to persist through 2028, if not longer. More importantly, clients are already interested in products scheduled for 2029 and 2030, underscoring the timing and intensity of AI demand, which the broader market still underestimates. These signals translate into solid results and improved guidance for ASML, with trends suggesting not only continued strength but also outperformance and potential acceleration in the coming quarters. ASML’s Mixed Quarter Overshadowed by Demand Signals and GuidanceASML reported a mixed quarter, with Q3 revenue falling slightly short of consensus estimates. However, the bar was high: nearly 100% of earnings forecasts had been raised since the last report, pricing in an immediate production ramp even though that was unlikely to occur. Third-quarter sales were supported by new and used machines, as well as services provided to the installed base. Installed-base revenue grew 19%, new-unit sales increased 31.3%, and used-unit sales rose marginally. Margin news was even better than the revenue results. Gross margin widened as a result of increased leverage and stronger sales, driving improved performance through to the bottom line. Although investments weighed on cash flow, the impact was minimal, leaving the company’s financial position stronger. Adjusted earnings per share beat estimates by 2,000 basis points, aided by a one-time gain, but still exceeded expectations when excluding that gain. Guidance sets the stage for future catalysts. The company raised the low end of its full-year guidance and issued a strong forecast for Q4. It will likely perform at the high end of its range, if not outperform it. Catalysts include next year’s guidance, which will reflect ASML’s planned 30% increase in chipmaking-equipment production capacity in 2027, as well as any additional capacity expansions the company announces. ASML’s Dividends, Buybacks and Bullish Signals Point to More UpsideAmong ASML’s attractions are its capital returns. The company pays dividends, buys back shares and could accelerate both programs in the coming year. The interim dividend is tracking the company’s established trend, with 10 years of steady, double-digit increases and a payout ratio below 20%. Share buybacks offset stock-based compensation and incrementally reduce the share count, boosting per-share earnings growth and investor leverage. Analysts expressed some caution about the capacity constraint, noting that it could hinder growth, but they are otherwise bullish on the stock. The 27 analysts tracked by MarketBeat reflect strong conviction in the consensus Moderate Buy rating and price target, which forecast approximately 25% upside as of mid-October. The trend is important, with price targets rising ahead of the release. High-end price targets suggest a move to the $2,600 range within 12 months, representing approximately 50% upside. Technical signals are equally bullish. As of mid-Q4, the market is consolidating but remains within an uptrend, suggesting that higher levels may follow. Support appears strong near $1,600, while the MACD shows a head-and-shoulders reversal pattern. Overall, the market appears positioned for a move higher. 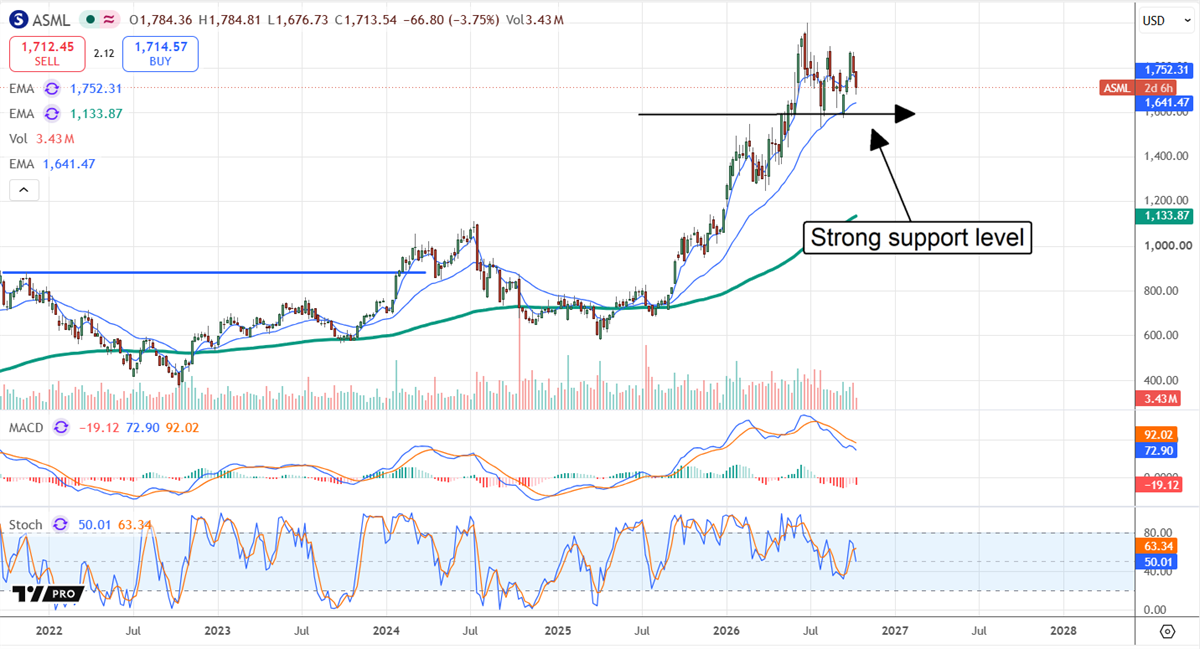
Critical resistance sits near the existing highs and could trigger additional capital inflows if broken. Assuming new highs are established, the patterns in place—including the consolidation and preceding rally—suggest that a $500 to $600 move could follow, enough to reach the analysts’ high target range. Don’t Mistake the Size and Depth of ASML’s MoatInvestors should not mistake ASML’s supply constraint for a weakness. The company has a deep moat as the only supplier of extreme ultraviolet lithography machines, which are essential for producing the most advanced, AI-capable chips. ASML can’t lose demand; it can only defer that demand until it can meet it. The question now becomes whether a capacity ramp is truly necessary, since oversupplying the market could have far-reaching, long-lasting repercussions. By not ramping capacity, ASML can extend its revenue and earnings visibility into the next decade. ASML’s biggest risk is disruption. Another company could develop a semiconductor-printing machine superior to its products. However, that risk appears slim, as there are no direct competitors today and emerging technologies remain far from commercial application. In this scenario, ASML is an execution story that needs only to meet demand at a steady pace, control costs and generate cash flow and capital returns for its stock price to continue moving higher. . |

Comments
Post a Comment